
Sterling Weakness Meets a New UK Refinancing Squeeze
1. THE DEVELOPMENT
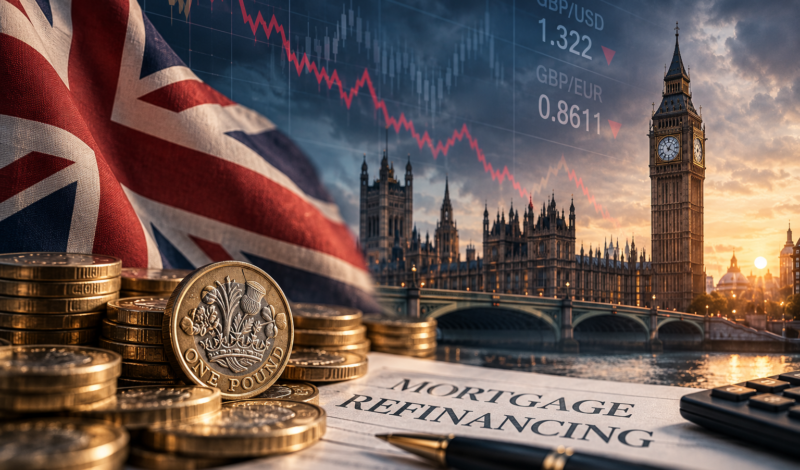
Sterling ended the week under renewed pressure. On 25 September, the pound traded around $1.322 after touching $1.32 the previous day, its weakest level against the dollar since 29 June. It was heading for a weekly decline of roughly 1.2%, following another 1% fall the week before. The euro also strengthened to 86.11 pence, taking sterling close to a three month low against both major currencies. Reuters attributed much of the move to stronger expectations of further US rate increases, rising energy prices and widening differences between expected central bank policy paths. MarketScreener India
The domestic backdrop is increasingly important. The Bank of England kept Bank Rate at 3.75% on 17 September, but the vote was 6 to 3, with three Monetary Policy Committee members preferring an immediate rise to 4%. Governor Andrew Bailey and several other members also made clear that persistent energy pressure could eventually require tighter policy. The Bank simultaneously committed to unwind its remaining £368 billion monetary policy gilt portfolio by 2034, including £20 billion of annual sales alongside maturities. Bank of England
2. THE PRIVATE WEALTH CONTEXT
The important change is not simply that UK rates are high. It is that the direction of travel has become less predictable. Earlier expectations centred largely on when the Bank of England might resume reducing rates. The current question is whether inflation generated by energy and geopolitical disruption could force the Bank to tighten again before meaningful easing becomes possible.
That matters because private borrowers rarely experience monetary policy through Bank Rate itself. They experience it through mortgage pricing, revolving facilities, corporate debt, development finance, private credit and refinancing terms. Market interest rates can therefore rise even when the central bank itself does nothing.
The Financial Times reported this week that around one million UK households have refinanced fixed rate mortgages since February, with many facing an additional £50 to £70 per month. Approximately 700,000 further households are expected to refinance before year end. For larger mortgages, the effect is materially greater. Financial Times
For international families, sterling adds another layer. A UK liability funded by euro, dollar or Swiss franc assets can become more or less expensive depending on currency moves. Equally, sterling weakness may make UK assets appear cheaper to overseas capital without improving their underlying economics. Currency, financing and valuation therefore need to be considered together.
3. WHY THIS MATTERS FOR CAPITAL
The combination of weaker sterling and higher expected UK rates creates a difficult mix. Higher yields increase financing costs and can compress valuations, particularly in leveraged property and businesses, while a softer currency changes returns for international investors. At the same time, tighter bank underwriting can redirect borrowers toward private credit, asset backed lending or liquidity secured against investment portfolios. Capital does not necessarily disappear in this environment, but it becomes more selective and more expensive.
4. WHAT WE ARE WATCHING NEXT
3 months: Energy prices, UK inflation and November’s Bank of England decision will determine whether the current tightening expectations persist.
6 months: Refinancing pressure should become more visible as additional fixed rate loans mature and businesses renegotiate facilities.
12 months: If inflation remains persistent, the UK could face an extended period in which borrowing costs remain structurally above the levels investors became accustomed to during the previous decade.
24 months: A normalisation of geopolitical conditions could eventually reopen the path to lower rates, although a return to ultra low borrowing costs should not be treated as the base case.
5. HOW PROFESSIONAL CAPITAL IS RESPONDING
Markets currently price around 35 basis points of additional Bank of England tightening this year and more than 100 basis points by the end of 2027, although many economists expect substantially less. That disagreement is itself significant. It tells us that investors are paying unusually high premiums for uncertainty around inflation and energy. MarketScreener India
Banks and lenders are consequently placing greater emphasis on debt service capacity, liquidity and collateral quality. Investors are also demanding higher yields from leveraged investments because government bonds now offer materially more competition for capital.
6. THE PRIVATE BANKING PERSPECTIVE
An experienced private banker would not look at the UK refinancing environment simply by asking whether rates are going up or down. The more useful questions concern the maturity profile of existing debt, the currency of liabilities, the liquidity available outside operating businesses and whether secured borrowing can be reorganised before a refinancing deadline becomes urgent.
For clients with substantial financial portfolios, the comparison between conventional borrowing and Lombard lending can also become relevant. A Lombard facility is credit secured against a portfolio of eligible securities. It can offer flexibility, but its economics depend on collateral composition, currency and loan to value. It should therefore be assessed as part of the client’s broader balance sheet rather than as an isolated source of cheap liquidity.
7. IMPLICATIONS FOR INTERNATIONAL CLIENTS
Entrepreneurs and families with UK property, business interests and assets held elsewhere should increasingly view financing, sterling exposure and liquidity as one conversation. Multi banking can reduce dependence on a single credit institution, while currency diversification and properly structured secured borrowing may provide additional flexibility where conventional refinancing becomes restrictive.
8. THE PRIVATE OFFICE VIEW
The important message is not that UK credit is unavailable. It is that the period of easy assumptions about refinancing is ending. International clients should understand their debt maturity calendar before the bank dictates the timetable, and evaluate liquidity, currency and collateral across their full international balance sheet rather than institution by institution.

